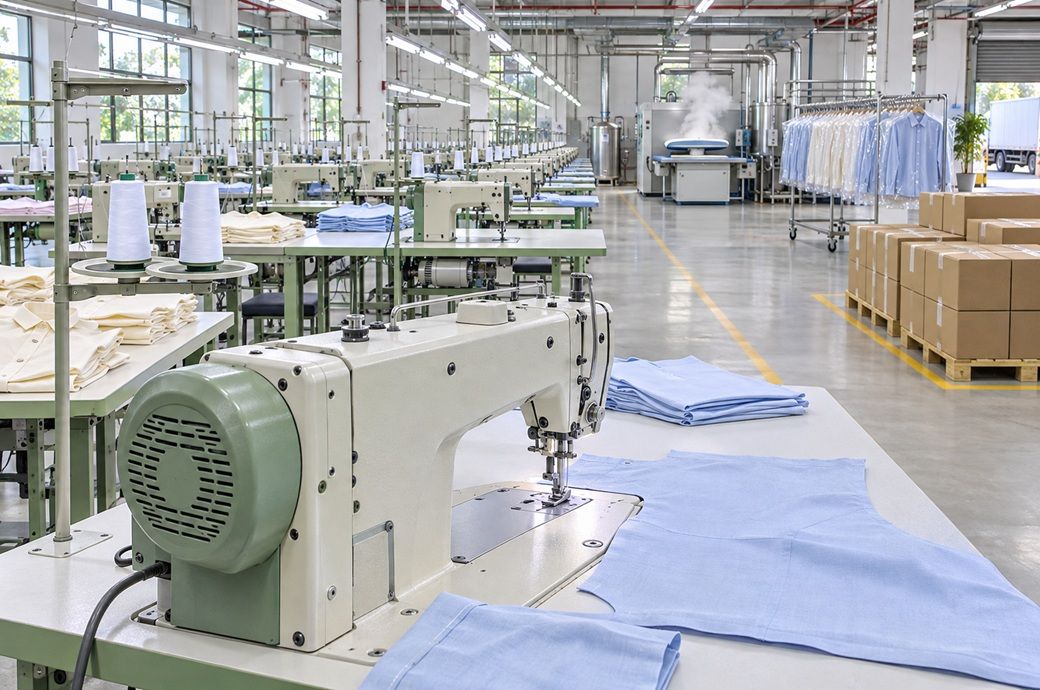
The stakes are considerable. Bangladesh’s readymade garment industry employs more than four million workers and accounts for around 80 per cent of the country’s merchandise export earnings.
Coming close on the heels of the recent energy crisis, which had already placed considerable pressure on the industry, the ongoing workers’ protests could have implications beyond immediate operational disruptions, with stakeholders expressing concern that such developments could influence buyers’ sourcing decisions over the short and long term.
Bangladesh garment protests have shut around 65 factories in Savar, Ashulia and Gazipur as workers seek a minimum wage rise to Taka 32,000 (~$256).
Another 56 reportedly declared holidays, deepening disruption after an energy crisis in a sector employing over four million and earning 80 per cent of merchandise exports.
Sustained delays could divert orders to India and hit Indian yarn suppliers.
While it is too early to establish whether the developments have had any impact on orders, they have nevertheless brought into focus the possibility that competing sourcing destinations could benefit if the disruptions persist.
Repeated production interruptions, shipment delays and uncertainty over delivery schedules could encourage global buyers to diversify sourcing to reduce dependence on a single destination.
India could emerge as a beneficiary, some industry observers believe. Its potential attractiveness is reinforced by an expanding network of trade agreements and growing engagement with key export markets. Additionally, the country’s strong domestic raw material base and extensive manufacturing capabilities underpin its appeal as a global textile and apparel sourcing destination.
As one of the world’s leading producers of cotton, India also has an established manmade fibre industry and manufacturing capabilities spanning the entire value chain, from fibre and yarn to fabric and finished garments.
However, India is not the only alternative; Vietnam has established itself as a major global textile and apparel manufacturing hub, supported by a strong export-oriented production base and preferential trade access through agreements such as the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) and the EU–Vietnam Free Trade Agreement. Vietnam’s strengths in manufacturing and its established relationships with international brands make it a strong competitor.
Pakistan is another relevant sourcing destination, with an established textile manufacturing base and capabilities spanning cotton spinning, fabric production, home textiles and garments. While its established cotton-based supply chain offers certain advantages, energy costs, economic conditions and the need for greater investment and improved manufacturing competitiveness remain important considerations.
The situation in Bangladesh also presents a potential downside for India’s textile stakeholders. Bangladesh reportedly accounted for approximately 49 per cent of India’s cotton yarn exports by value in FY2024–25, making it an important market for Indian spinning mills. Prolonged factory disruptions could therefore affect Indian yarn suppliers through weaker or deferred procurement demand.
Meanwhile, although garment workers’ wages in Bangladesh remain considerably lower than those in many competing manufacturing destinations, industry stakeholders have reportedly cautioned that a substantial increase in minimum wages could add to manufacturers’ cost pressures. This is particularly relevant in a highly labour-intensive industry that operates on relatively tight margins and remains sensitive to buyers’ pricing expectations.
Despite the recent challenges, first from the energy crisis and now from labour protests, Bangladesh’s established manufacturing scale and sourcing ecosystem continue to make it an important destination for global buyers. According to industry stakeholders, it is still too early to assess the implications, and any potential impact would depend on how the situation evolves and whether it results in sustained disruptions to production and deliveries.
Fibre2Fashion News Desk (DR)