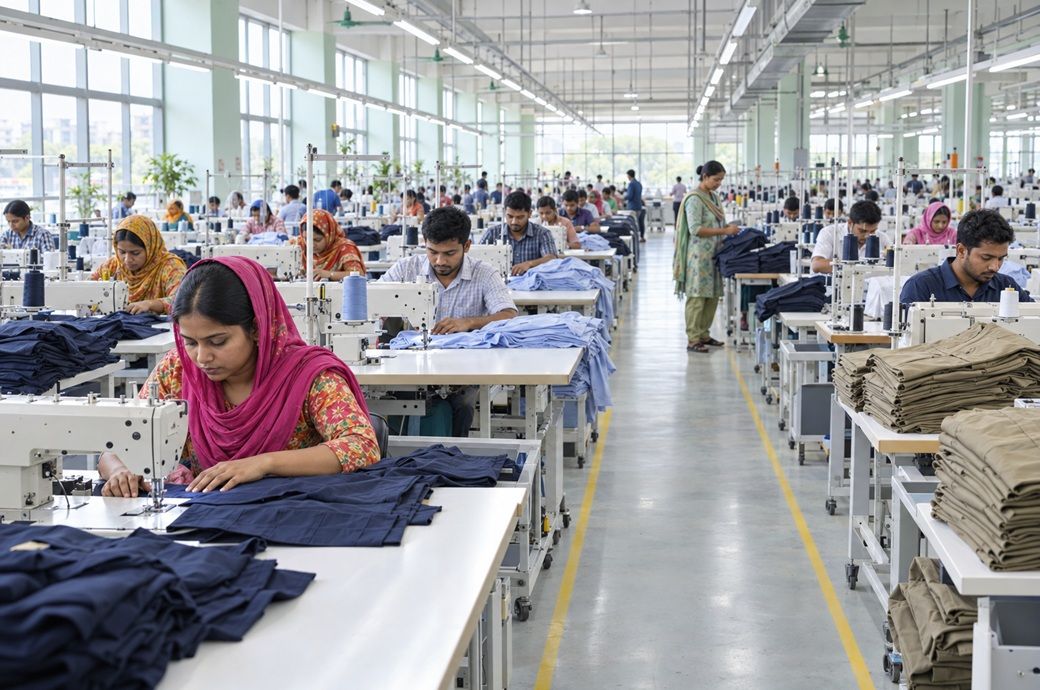
Recent media reports suggest some major international fashion retailers are overhauling their global sourcing networks to spread operational, geopolitical and energy risks, with some long-time buyers reportedly shifting work orders from Bangladesh.
According to reports, the Bangladesh Garment Manufacturers and Exporters Association (BGMEA) president has also acknowledged the shift, adding that buyers were increasingly spreading sourcing rather than relying on a single country. For Bangladesh, that is more than a routine change: once buyers start factoring country-level risks more heavily into sourcing, cost and product quality are no longer the only variables.
Bangladesh apparel faces buyer diversification as retailers reassess sourcing exposure, country risks and post-LDC trade uncertainty.
EU EBA access will remain for three years after graduation, but Vietnam already has an EU FTA and India is improving access.
Recent gas shortages disrupted production and shipments, making durable energy supply and a longer-term EU trade deal critical.
Least developed country (LDC) graduation is one of those risks, it seems. Bangladesh remains scheduled to graduate on November 24, 2026, although the government has sought a three-year deferment and the process is still pending. The uncertainty matters because LDC preferences underpin Bangladesh’s competitiveness in several major export markets, and graduation does not produce the same outcome in each one.
Buyers therefore have to assess not just when Bangladesh graduates, but what tariff treatment follows in the markets where they source from the country.
The European Union (EU) is of particular importance. Bangladesh will retain Everything But Arms (EBA) preferences for three years after graduation, so there is no immediate loss of duty-free access. Under the current EU arrangement, the benefit runs three years post-graduation. But that gives Bangladesh a window, not a permanent solution.
And the competition inside that window is moving. Vietnam already has an EU free trade agreement (FTA). The EU and India concluded negotiations on their FTA in January, with most tariffs on Indian textiles and apparel set to be removed once it takes effect.
According to estimates, Bangladesh shipped €19.41 billion (~$21.8 billion) of apparel to the EU in 2025 and accounted for 21.57 per cent of the bloc’s apparel import market. The scale of the business makes the comparison with India and Vietnam difficult to dismiss: European buyers are gaining more preferential sourcing options whilst Bangladesh’s post-EBA position remains unsettled.
Energy has meanwhile added a very immediate concern. The recent gas shortage disrupted industrial production and affected shipment schedules, whilst industry groups reported order cancellations and reductions.
One industry survey reportedly found 55 per cent of surveyed knitwear factories had experienced reduced or cancelled orders, 78 per cent partial production shutdowns and 87 per cent shipment delays during the disruption.
According to some reports, factories also faced higher costs from alternative fuel and transportation.
The situation has reportedly improved considerably since. Petrobangla (the state-owned national oil company of Bangladesh) data showed gas supply rising to around 2,600 mmcfd in late September from about 2,300 mmcfd a month earlier, after liquefied natural gas (LNG) supplies recovered.
Reports from industry areas also indicated that production has been picking up since, even as the BGMEA president also acknowledged the gas situation had improved significantly.
The bigger question, even if the immediate pressure is easing, is whether the improvement will hold.
That matters because the energy disruption came at precisely the wrong time. Buyers were already reassessing sourcing strategies, and Bangladesh has now given them another variable to consider. A country competing for orders with Vietnam, India and others cannot afford repeated uncertainty over whether factories can maintain production and shipment schedules.
Meanwhile, the BGMEA chief reportedly said that buyers will not necessarily source all their products from one country and that BGMEA was working to attract new buyers whilst encouraging existing ones to increase sourcing from Bangladesh.
He, however, argued that Bangladesh should seek an FTA with the EU within three to four years rather than rely on Generalised Scheme of Preferences Plus (GSP Plus).
The argument is particularly relevant now. Bangladesh will retain EBA preferences in the EU for three years after LDC graduation, which would provide additional time. The priority thus should be to use this window to negotiate a longer-term trade arrangement with the EU, rather than allow uncertainty over post-EBA access to become a factor in buyers’ sourcing decisions.
Industry insiders emphasised that the government also needs to make the recent improvement in gas and electricity supply durable. The two issues—trade preferences and energy reliability—are different, but they arrive at the same place: the buyer deciding where the next order goes.
Bangladesh has the factories, capacity and established buyer base. But India is improving its access to the EU whilst Vietnam already has preferential access, and buyers seem more than keen on spreading the risks.
So, whilst Bangladesh is still debating its post-LDC trade future and recovering from an energy shock, the question now is not whether Bangladesh can attract buyers, but whether it can give them enough reasons not to look elsewhere.
Fibre2Fashion News Desk (DR)